Understanding an Oklahoma Roof Claim
Published · Updated 2026-10-03
A roof claim involves two connected decisions: what work the roof needs and what the policy pays. Keeping those questions distinct helps avoid a repair estimate being mistaken for a coverage promise.
If the roof is leaking, tell Jenks Roofing Pros whether water is entering now. Request a free inspection for the roofing concern while using your insurer’s actual reporting process for the claim.
Address the immediate condition safely
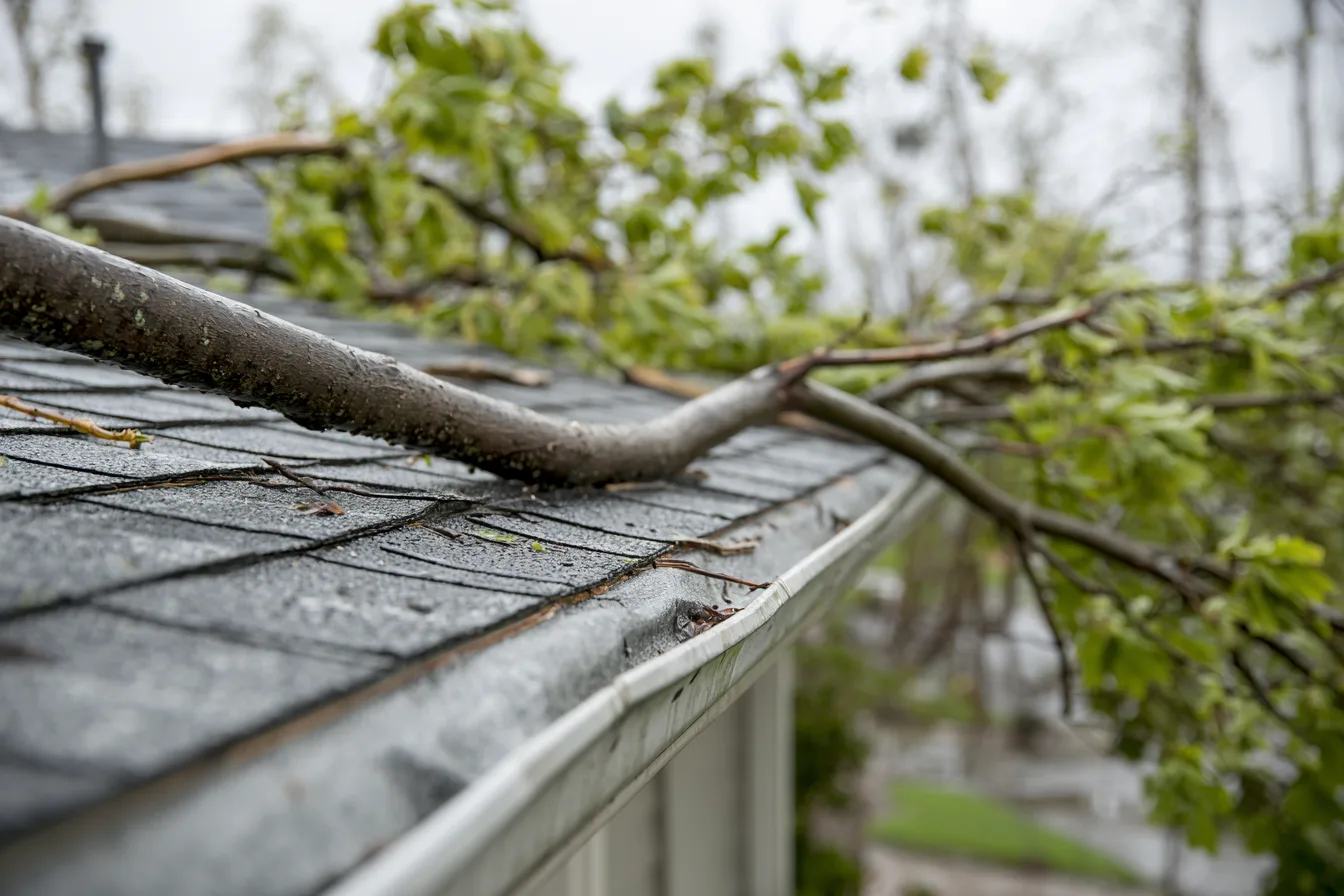
Stay off a storm-damaged roof. Keep people away from unstable areas, sagging ceilings and wet electrical fixtures. If the situation presents an immediate emergency, get the appropriate emergency assistance as well as roofing help.
Temporary roof protection and permanent restoration have different purposes. Their feasibility depends on safe access and the affected material. Mention current water entry first so the roofing conversation starts with the urgent condition.
Report through the insurer’s actual process
Your insurer’s reporting requirements and policy terms control the claim. Do not assume a roofing inspection must happen before you can notify the insurer. Give the event and visible concern accurately, without guessing at damage you have not seen.
Existing photos, event records and invoices can help explain the loss. You do not need to climb onto the roof to create a damage inventory. The insurer and roofer can carry their respective assessments.
The roof inspection develops the physical work
The roofer examines the affected covering and details, along with surrounding condition. A repair needs sound adjoining material; broad deterioration or damage can shift the discussion toward replacement.
An indoor leak can involve concealed layers or water travel from another part of the roof. The scope may require investigation beyond the visible stain. The inspection should explain what is established and which conditions remain unknown.
Understand deductible and valuation before assuming payment
A covered loss can still leave a deductible and costs not covered by the policy. Roof valuation may use actual cash value or other roof-specific provisions. Replacement-cost payment can have conditions for further payment after work.
The Oklahoma Insurance Department’s post-disaster guide explains these valuation distinctions. They provide consumer context, not a determination of your claim. The actual policy and insurer’s explanation need to be understood together.
Read the OID post-disaster claims guide.
Clarify differences between the claim and roofing scope
A claim determination and a proposed roofing agreement may describe different items or quantities. That difference needs explanation rather than an assumption that either total alone settles the project.
Know what work is included, how concealed damage will be handled and which amount remains your responsibility. A manufacturer warranty, material upgrade or interior restoration also has a different role from the roof damage claim.
Request an inspection of the roof damage
Our roof insurance guide develops policy terms and payment boundaries. Storm damage roofing explains the material and repair decisions.
For the actual roof condition, request a free inspection with Jenks Roofing Pros. The insurer remains responsible for coverage and claim payment.